
Before purchasing a property in Catalonia, the seller must obligatorily provide a key document for the legal security of the transaction: the certificate of outstanding debts with the owners' association (comunidad de propietarios).
This procedure is much more than a simple bureaucratic formality prior to signing at the notary. In the real estate sector, it is common to focus solely on checking whether the seller is up to date with monthly fees, neglecting future financial commitments already approved by the homeowners' board. For this reason, carrying out a complete property review before committing funds is the best guarantee for the buyer.
What is the certificate of outstanding community debt?
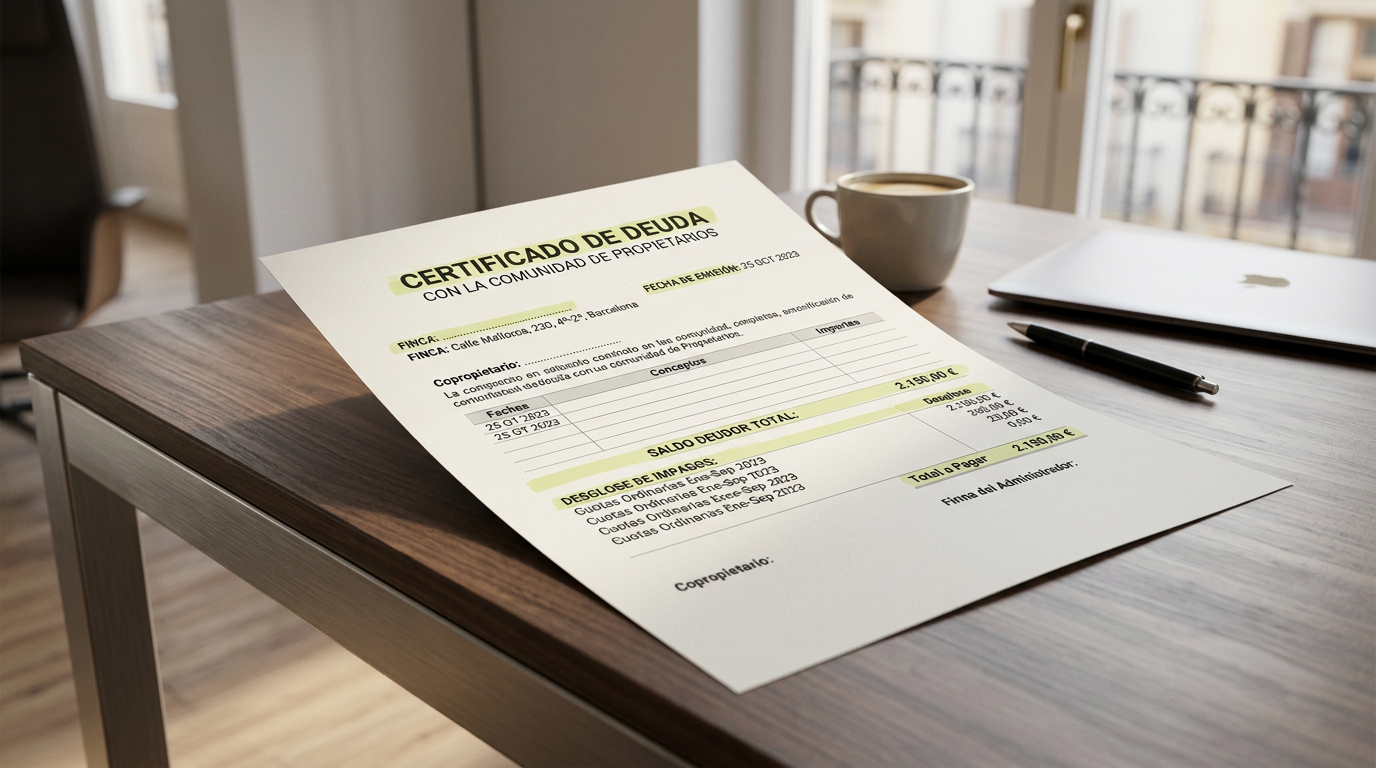
The outstanding community debt certificate is an official document issued by the building's secretary that certifies the financial status of a specific property regarding common expenses.
Its primary purpose is to provide transparency to the purchase and sale, informing the buyer if there are any ongoing financial claims or outstanding balances linked to the property. These balances may stem from:
- Ordinary fees: Regular maintenance costs of the building (cleaning, electricity, driveways, concierge).
- Extraordinary fees: Special assessments (derramas) approved for contingencies or improvements.
- Reserve fund: Legal contributions aimed at guaranteeing the future maintenance of the community facilities.
In Catalonia, regulations are particularly strict in this regard, forcing the transferor to declare the status of their community obligations and to provide this certificate in order to elevate the contract to a public deed.
What must the certificate include in Catalonia?
According to Article 553-5 of the Civil Code of Catalonia (Código Civil de Cataluña), it is not enough for the document to state generically that the owner is 'up to date with payments'. To strictly comply with Catalan regulations, the document must detail:
- Liquid and matured debts pending payment.
- Budgeted ordinary expenses that are not yet due.
- Extraordinary expenses (special assessments) already approved by the owners' board whose maturity is subsequent to the transfer.
- Pending contributions to the reserve fund agreed upon by the community.
The danger of approved but not yet due special assessments
This nuance of Catalan legislation is of vital importance. Imagine a scenario where the owners' board has approved a facade renovation for a total cost of €12,000 per neighbor, split into twelve monthly installments of €1,000. If at the time of sale four installments have been paid and there are no returned receipts, the seller is technically 'up to date with payments'. However, there is a future payment obligation already accrued of €8,000.
If the certificate only indicated that the seller has no unpaid bills, the buyer would be unaware of this €8,000 financial burden. The certificate must reflect these outstanding, not-yet-due amounts so that the parties can negotiate their assumption in the earnest money agreement (contrato de arras).
Who issues and signs this document?
By law, the issuance of the document corresponds to whoever performs the functions of secretary of the community.
In the vast majority of homeowners' associations (comunidades de propietarios), this task is delegated to a professional property manager (administrador de fincas). When the administration of the property has a qualified professional who also acts as secretary, the civil legislation of Catalonia (Código Civil de Cataluña) dictates that the certificate is valid with their signature alone, without mandatorily requiring the approval or additional signature of the president of the association.
It is essential that the document is duly dated and signed on dates very close to the sale and purchase. A certificate issued three months ago does not guarantee the absence of debts accumulated in the weeks prior to the signing before the notary.
Is it mandatory to provide the certificate in the deed?
Yes, it is a legal requirement demanded by the notary to authorize the public deed of sale and purchase. The Código Civil de Cataluña (Civil Code of Catalonia) itself stipulates that notaries will not authorize the execution of the deed if the transferor does not provide this certificate or if their sworn declaration is not incorporated.
However, the law allows the buyer to expressly waive the provision of this document at the time of signing.
Why is it never advisable to waive the certificate?
Under no circumstances is it advisable to accept the waiver of the certificate of outstanding community debts. When buying a home, the property itself becomes legally liable (afección real) for the payment of outstanding community expenses.
Within the framework of Catalonia's civil law, what is known as afección real (real encumbrance) operates. This implies that the apartment is legally liable for the debts of the previous owner regarding:
- The expired fraction of the current calendar year at the time of transfer.
- The four immediately preceding calendar years (counted backwards from January 1 of the year of purchase).
If the seller carries significant debts from the last three years and you waive the certificate at the notary's office, the homeowners' association may direct its enforcement claims directly against your newly acquired home. Although you retain the legal right to claim this amount back from the original seller through legal channels, for practical purposes you will have to pay the debt to avoid the foreclosure of your home.
Debt Certificate vs. Association Minutes: Why you need both
The certificate offers a strict snapshot of the settled monetary debts and already approved payment agreements. However, it does not provide all the necessary information about the financial and structural health of the building. To obtain a complete picture, it is essential to cross-reference the debt certificate with other key documents:
- Minutes of the owners' meetings: It is essential to review the latest association minutes. In them, you can detect if there are special assessments (derramas) under study, active lawsuits between neighbors, or recurring delinquency problems in the building.
- Inspección Técnica de Edificios (ITE): It is advisable to check the status of the ITE (Technical Building Inspection) to anticipate whether the property has serious or very serious deficiencies that will force the approval of substantial special assessments (derramas) in the short term.
The combination of a comprehensive certificate, the last three minutes of the owners' meetings, and the ITE report constitutes the core of a fully guaranteed purchasing audit.
What to do if the certificate reveals debts or special assessments?
If the examination of the certificate reveals that the seller has outstanding debts or there are approved unpaid special assessments, there are several legal solutions that must be firmly set down in writing from the preparatory stage and be present in the documentation before signing the earnest money agreement:
- Settlement prior to signing: Formally require the seller to contact the property management company, settle the entirety of their debt prior to the public deed of sale, and provide a new certificate with a zero balance.
- Withholding of the sale price: It is agreed in the earnest money contract (contrato de arras) that the buyer will withhold from the amount to be paid at the notary's office the exact amount owed to the community, with the buyer committing to settle it directly with the property manager after the signing of the deed.
- Express agreement on future special assessments: In the case of already approved special assessments whose monthly payments extend over time, it must be clarified without ambiguity who pays the outstanding special assessments. The recommended approach is to deduct from the sale price the total value of the outstanding extraordinary fees, with the buyer assuming the future payment of the receipts.
It is worth remembering that the reserve fund built up over the years in the community legally belongs to the property itself and not to the individual owner. Therefore, the seller has no right to claim from the buyer the refund of their share in said fund.
Conclusion
When acquiring a property, community fees in a sale represent a recurring financial commitment that can destabilize your budget if there are hidden charges. Requiring a complete and detailed community debt certificate, which strictly complies with the Civil Code of Catalonia (Código Civil de Cataluña), is an essential step to buy with total peace of mind and protect your assets against third-party debts.
Before signing the deposit
If you are considering buying in Barcelona, read the full guide: Buying a flat in Barcelona without surprises.